
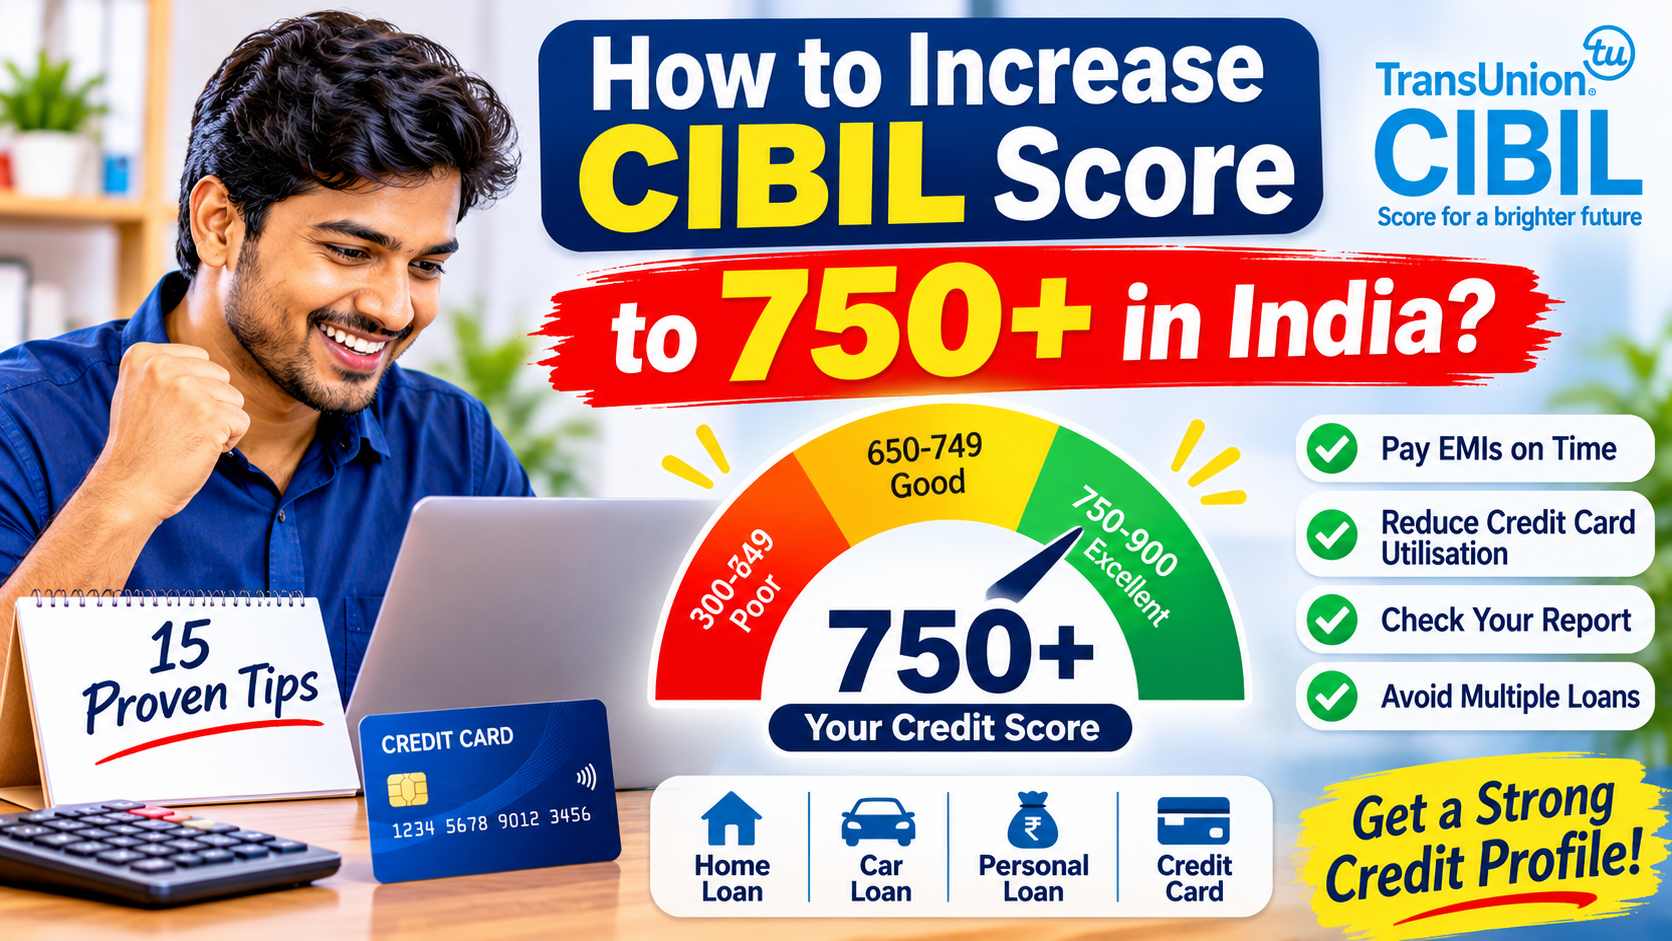
How to Increase CIBIL Score to 750+ in India: 15 Proven Ways to Improve Your Credit Score
Are you planning to apply for a home loan, personal loan, business loan or credit card but worried about your CIBIL score?
Your credit score plays an important role when banks and NBFCs evaluate your loan application. A low credit score can make it difficult to obtain financing, while a strong credit history can improve your chances of getting your application considered.
In India, TransUnion CIBIL provides a three-digit credit score ranging from 300 to 900. Generally, a score closer to 900 indicates a stronger credit profile.
If your current CIBIL score is below 650 or 700, don’t panic. There are several practical steps you can take to improve your credit history and build a healthier financial profile.
In this detailed guide, we explain how to increase your CIBIL score to 750 or above, how long it may take, common mistakes to avoid, and how to check your free CIBIL report in 2026.
What Is a CIBIL Score?
A CIBIL score is a three-digit number that represents your credit history and repayment behaviour.
Banks, housing finance companies, NBFCs and other financial institutions use credit reports and scores as part of their loan assessment process.
Your CIBIL score generally falls within the following range:
| CIBIL Score | General interpretation |
|---|---|
| 300–549 | Weak credit profile |
| 550–649 | Needs improvement |
| 650–699 | Fair credit profile |
| 700–749 | Good credit profile |
| 750–799 | Strong credit profile |
| 800–900 | Excellent credit profile |
These are general educational categories, not official CIBIL rating bands. Individual lenders may use different internal credit policies.
Is 750 a good CIBIL score?
Yes. A CIBIL score of 750 or above is generally considered a strong score by many lenders. However, a good credit score does not guarantee loan approval.
Banks also consider your income, employment stability, existing EMI obligations, repayment capacity, property details and internal lending policies.
Why Is Your CIBIL Score Important?
Your credit score can influence several financial decisions.
1. Home Loan Approval
When you apply for a home loan, the lender evaluates your credit history along with your income, property documents and repayment capacity.
A stronger credit profile may improve your chances of getting your home loan application considered.
2. Personal Loan Eligibility
Personal loans are generally unsecured loans. Therefore, lenders may pay considerable attention to your credit history and repayment behaviour.
A poor credit history can result in rejection, lower eligibility or less favourable loan terms.
3. Credit Card Approval
Credit card companies evaluate your credit history, income and existing obligations before issuing a credit card.
A good score can improve your chances of qualifying for suitable credit cards.
4. Interest Rate and Loan Terms
Some lenders consider credit scores when determining loan pricing and terms. A strong credit profile may help you qualify for more favourable terms, depending on the lender’s policy.
5. Financial Credibility
Your repayment history reflects how responsibly you manage borrowed money.
Maintaining a healthy credit profile can help when you need financing in the future.
15 Proven Ways to Increase Your CIBIL Score to 750+
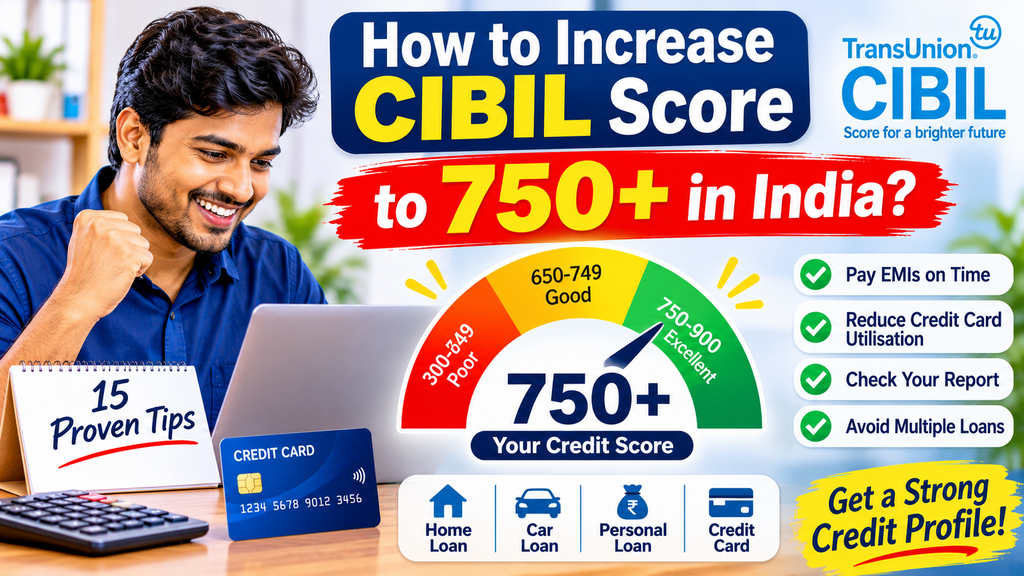
Let’s look at practical steps that can help you build a better credit profile.
1. Always Pay Your EMI Before the Due Date
Payment history is one of the important factors affecting your credit score.
If you miss your home loan EMI, personal loan EMI, vehicle loan EMI or credit card payment, the lender may report the delay to credit information companies.
Even a short payment delay can affect your credit profile.
What should you do?
- Pay your EMIs before the due date.
- Maintain sufficient balance in your bank account.
- Activate EMI reminders.
- Set up an automatic payment facility where appropriate.
- Avoid waiting until the last day to make payments.
If you have multiple loans, prepare a monthly EMI calendar.
2. Keep Your Credit Card Utilisation Low
Credit utilisation refers to the percentage of your available credit limit that you are using.
For example:
| Particulars | Amount |
|---|---|
| Credit card limit | ₹1,00,000 |
| Current outstanding | ₹70,000 |
| Utilisation | 70% |
A high utilisation ratio may indicate that you are relying heavily on available credit.
As a practical approach, try to keep your utilisation below 30%, preferably lower when possible.
For example, if your credit limit is ₹1 lakh, try to keep your reported outstanding below ₹30,000.
Remember that 30% is a commonly used guideline, not a guaranteed CIBIL scoring threshold.
3. Avoid Applying for Multiple Loans at the Same Time
Every time you apply for a loan or credit card, the lender may make a credit enquiry.
Several enquiries within a short period can negatively affect your credit profile.
For example, imagine that you are planning to purchase a house.
You submit applications to five different banks within one week without comparing their eligibility requirements.
Each application may generate a separate credit enquiry.
Better approach:
- Compare lenders before applying.
- Check your eligibility first.
- Submit applications only to suitable lenders.
- Avoid unnecessary credit card applications.
You can check your own credit score without worrying that the self-check itself will reduce your score.
4. Check Your CIBIL Report for Incorrect Information
Sometimes your credit report may contain incorrect information.
Examples include:
- A loan that you have already closed showing as active.
- An incorrect overdue amount.
- A payment marked late despite being paid on time.
- A loan account that does not belong to you.
- Duplicate loan accounts.
- Incorrect personal information.
These errors should be investigated.
How to correct an error:
- Download your credit report.
- Identify the incorrect account or information.
- Collect relevant payment receipts, NOCs or loan closure documents.
- Raise a dispute with TransUnion CIBIL.
- Contact the concerned bank or NBFC as well.
- Follow up until the discrepancy is resolved.
Do not pay any unofficial agent who promises to delete genuine negative credit history.
5. Close Overdue Credit Card Dues
If you have unpaid credit card dues, prioritise clearing them.
Outstanding credit card balances can affect your financial profile and may continue to accumulate interest and charges.
Try to pay the full outstanding amount rather than making only the minimum payment.
If you cannot pay everything immediately, contact the credit card issuer and ask about available repayment options.
Remember that paying an overdue amount does not automatically erase previously reported late payments.
6. Avoid Credit Card Settlement Unless Necessary
Credit card settlement is different from full repayment.
When you settle a credit card account for less than the total amount owed, the lender may report the account as settled rather than closed.
This can negatively affect your credit history and future borrowing opportunities.
If financially possible, try to repay the full outstanding amount and obtain a proper closure confirmation.
If you have already settled an account, check how it is reflected in your credit report.
7. Maintain a Healthy Credit Mix
A credit mix refers to the different types of credit accounts in your credit history.
Examples include:
- Home loans
- Vehicle loans
- Personal loans
- Credit cards
- Business loans
A balanced credit profile can demonstrate experience managing different forms of credit.
However, you should never take a new loan simply to improve your credit score.
Borrow only when you genuinely need credit and can comfortably repay it.
8. Avoid Being a Guarantor Without Understanding the Risk
Many people agree to become guarantors for friends or relatives without understanding the financial responsibility involved.
If the primary borrower fails to repay the loan, the guarantor may also become responsible under the loan agreement.
Missed payments on guaranteed or jointly held accounts can affect your credit profile.
Before becoming a guarantor, carefully understand the repayment obligations.
9. Monitor Joint Loan Accounts
If you have taken a joint home loan or another joint credit facility, remember that repayment behaviour on the account may affect both borrowers.
If one applicant fails to pay the EMI, the other applicant’s credit history may also be affected.
Therefore, regularly monitor all joint loan accounts.
10. Do Not Close Your Old Credit Card Without a Reason
The age of your credit accounts can be relevant to your credit profile.
An older credit card with a good repayment history may contribute to the length of your credit history.
Closing an old credit card can affect your available credit limit and overall utilisation ratio.
Before closing a card, consider:
- Annual maintenance fees.
- Credit limit.
- Outstanding balance.
- Account history.
- Whether the card is useful.
If the card has no unnecessary charges and you manage it responsibly, keeping it open may be worth considering.
11. Avoid Paying Only the Minimum Due
Credit card statements generally show a minimum amount due and a total amount due.
Paying only the minimum amount may prevent the account from immediately becoming overdue, depending on the terms, but interest can continue accumulating on unpaid balances.
This can create a debt cycle.
Try to pay the total amount due before the payment deadline.
12. Check Your Credit Report Every Month
Regularly reviewing your credit report helps you identify mistakes and suspicious activities.
You can check:
- Active loan accounts.
- Closed loan accounts.
- Credit card balances.
- Payment history.
- Outstanding dues.
- Credit enquiries.
Checking your own credit score does not create a hard enquiry in the same way as a lender’s credit application.
13. Avoid Taking Too Many Unsecured Loans
Personal loans and credit cards are examples of unsecured credit.
Having multiple unsecured loans with high outstanding balances may make lenders cautious.
If you already have several personal loans, focus on reducing your existing obligations rather than taking additional loans.
A lower debt burden can also improve your overall loan eligibility.
14. Maintain Consistent Financial Behaviour
Improving your credit score is not a one-day activity.
You need to maintain consistent repayment behaviour over time.
Follow these habits:
- Pay every EMI on time.
- Keep credit card utilisation under control.
- Avoid unnecessary borrowing.
- Check your credit report.
- Correct inaccurate information.
- Maintain sufficient funds for scheduled repayments.
Consistency is more important than trying shortcuts.
15. Allow Time for Your Credit Report to Update
Banks and financial institutions report credit information periodically.
After making a payment or closing a loan, it may take time for the updated information to appear in your credit report.
If your lender has not updated the information after a reasonable period, contact the lender and raise a dispute with the relevant credit information company.
There is no guaranteed number of days in which every person’s score will improve.
How Long Does It Take to Increase CIBIL Score From 600 to 750?
This is one of the most common questions among borrowers.
The answer depends on why your credit score is low.
For example:
| Current situation | What you should do |
|---|---|
| Score is low due to high credit utilisation | Reduce outstanding balances |
| Score is low due to missed EMIs | Build a consistent repayment record |
| Incorrect loan information | Raise a dispute |
| Multiple recent enquiries | Avoid unnecessary applications |
| Settled or written-off accounts | Discuss repayment and reporting status with the lender |
Some improvements may appear after credit information is updated. However, rebuilding a history affected by repeated missed payments or serious defaults can take considerably longer.
Important: Nobody can guarantee that a CIBIL score will increase from 600 to 750 within 30 days or 90 days.
Be careful with companies advertising guaranteed credit score improvement.
How to Check Your Free CIBIL Score Online in India
You can obtain your free annual CIBIL Score and Report directly from the official TransUnion CIBIL website.
Follow these steps:
Step 1: Visit the official website:
Step 2: Select the option to get your free CIBIL Score and Report.
Step 3: Enter the required personal information.
Step 4: Complete the identity verification process.
Step 5: Access your CIBIL Score and Credit Information Report.
The report includes information about your credit accounts, payment history and credit enquiries.
Important: TransUnion CIBIL provides one free full credit report, including the score, once per calendar year.
You can also use other authorised credit information companies to access your credit information.
What Is the Difference Between CIBIL Score and Credit Report?
Many people assume that their credit score and credit report are the same.
However, they are different.
| CIBIL Score | CIBIL Report |
|---|---|
| Three-digit number | Detailed credit history |
| Ranges from 300 to 900 | Contains account information |
| Indicates creditworthiness | Shows repayment behaviour |
| Used during loan assessment | Helps lenders evaluate your credit history |
| A summary of credit health | Detailed financial credit record |
Both are important when applying for a loan.
Can You Get a Home Loan With a CIBIL Score Below 700?
Yes, it may be possible, depending on the lender’s credit policy and your overall financial profile.
Some banks and NBFCs may consider applications with lower credit scores after evaluating other factors.
These may include:
- Monthly income.
- Employment stability.
- Existing EMI commitments.
- Loan-to-value ratio.
- Property legal and technical documents.
- Previous repayment history.
- Nature of credit defaults.
- Co-applicant income and credit history.
However, a low credit score may reduce your chances of approval or result in less favourable terms.
If you are planning to purchase a property, it is better to review your credit report before submitting a home loan application.
Can You Improve Your CIBIL Score Without Taking a New Loan?
Yes.
You do not need to take a new loan to improve your credit score.
In fact, taking unnecessary loans can increase your financial burden.
Instead, focus on:
- Clearing overdue payments.
- Paying existing EMIs on time.
- Reducing credit card utilisation.
- Avoiding multiple credit enquiries.
- Correcting inaccurate credit report information.
- Maintaining existing credit accounts responsibly.
A strong repayment history is more important than borrowing additional money.
Common Myths About CIBIL Score
Let’s clear up some common misunderstandings.
Myth 1: Checking your own CIBIL score reduces your score.
Fact: Checking your own score is a self-enquiry and does not reduce your score.
Myth 2: Closing a loan immediately increases your CIBIL score.
Fact: Loan closure updates your credit report, but the effect on your score depends on your overall credit history.
Myth 3: Taking a personal loan will automatically improve your CIBIL score.
Fact: A new loan is not a guaranteed way to improve your score. Unnecessary borrowing may create additional financial risk.
Myth 4: Paying an overdue amount immediately removes all negative history.
Fact: Paying overdue amounts improves your account status, but previously reported late payments may remain in your credit history.
Myth 5: A score of 750 guarantees home loan approval.
Fact: Lenders consider several factors beyond the credit score.
CIBIL Score Improvement Checklist
Before applying for your next loan, use this checklist:
- Check your latest CIBIL Score.
- Download and review your credit report.
- Pay all overdue EMIs.
- Clear outstanding credit card dues.
- Keep credit card utilisation low.
- Avoid unnecessary loan applications.
- Check for incorrect loan accounts.
- Raise disputes for inaccurate information.
- Obtain NOCs for closed loans.
- Monitor joint and guaranteed accounts.
Following these steps can help you build a healthier credit profile over time.
Frequently Asked Questions (FAQs)
1. What is a good CIBIL score for a home loan in India?
A score of 750 or above is generally considered strong. However, individual banks and housing finance companies have their own credit policies and eligibility requirements.
2. How can I increase my CIBIL score from 650 to 750?
Pay your EMIs on time, reduce credit card utilisation, avoid multiple loan enquiries and correct errors in your credit report. The time required depends on your existing credit history.
3. Does paying credit card bills on time improve CIBIL score?
Yes. Timely credit card payments help maintain a positive repayment history and support a healthy credit profile.
4. How many times can I check my CIBIL score for free?
TransUnion CIBIL provides one free full credit report per calendar year. Other services may have different pricing and access arrangements.
5. Can I get a personal loan with a 650 CIBIL score?
Some lenders may consider applicants with a 650 score, but approval depends on their credit policy, income, repayment capacity and other eligibility requirements.
6. Does a CIBIL score of 900 guarantee loan approval?
No. A score of 900 represents the top end of the scoring range, but lenders still evaluate income, obligations, documents and other risk factors.
7. Can a person with no credit history get a CIBIL score?
A person with insufficient credit history may receive an NA or NH status instead of a numerical score. Building a responsible credit history over time can help establish a score.
8. Does a home loan improve CIBIL score?
A home loan with consistent, timely repayments can contribute positively to your credit history. However, the overall effect depends on your complete credit profile.
9. How long does a settled loan remain in a credit report?
The reporting and retention of account information depend on applicable credit reporting rules and the credit information company’s records. Settlement does not automatically erase the account history.
10. Can CIBIL remove genuine loan defaults?
CIBIL cannot independently remove accurate information supplied by lenders simply because a borrower requests it. Incorrect information can be disputed and investigated.
Final Words
Your CIBIL score is an important part of your financial life. Whether you are planning to purchase your first home, buy a vehicle, apply for a personal loan or obtain a new credit card, maintaining a healthy credit history can make a difference.
Start by checking your credit report, clearing overdue payments and maintaining consistent repayment habits.
Do not believe advertisements promising an instant increase in your CIBIL score. There is no shortcut to building a strong credit history.
A good credit score is built through responsible borrowing and disciplined repayment behaviour.
Bookmark this guide and share it with anyone planning to apply for a loan in India.
Disclaimer
This article is intended for general financial education and awareness. Credit score calculations, lender eligibility requirements and loan approval policies may vary. A good credit score does not guarantee loan approval. Readers should verify information with TransUnion CIBIL and their respective lenders before making financial decisions.
Official References
- TransUnion CIBIL: https://www.cibil.com/
- Free CIBIL Score: https://www.cibil.com/freecibilscore
- RBI: https://www.rbi.org.in/
Focus keyword
How to Increase CIBIL Score
Secondary keywords
- Improve CIBIL score to 750
- CIBIL score improvement tips
- How to improve credit score in India
- Check free CIBIL score online
- CIBIL score for home loan
- Increase credit score fast
- Credit score improvement 2026
Share this content: